


You have revenue and a real operation, but repeated applications have produced denials, hard inquiries, and no clear explanation of what to strengthen first.
Assessbefore applying
T
The Denied Owner
Established business, unclear profile gaps
The Auxano Foundation Method™
Stop applying blind. Auxano helps individuals and business owners structure fundable personal and business credit profiles, prepare for underwriting, and use debt strategically to pursue cash flow, ownership, and generational wealth.
Sound Familiar?
Federal Reserve research shows owners are navigating rising costs, uneven cash flow, incomplete financing, and growing pressure from existing debt. Preparation gives you a better next move than panic.
A decision letter rarely explains how your debt load, utilization, documentation, entity, and cash flow looked together to underwriting.
You formed an LLC, but lenders still ask for your personal credit and guarantee because the business has not built enough independent strength.
Inconsistent records, thin business credit, weak banking history, and missing documentation can make a real company difficult to underwrite.
Short repayment cycles and costly financing can leave too little room for payroll, inventory, marketing, or the next opportunity.
More applications do not solve a readiness problem. They create frustration while the same structural gaps remain unresolved.
You can see the inventory, property, equipment, or contract that could create wealth—but you do not have a responsible capital path to pursue it.
"Do not ask only, ‘How much can I borrow?’ Ask, ‘Is my profile ready, and what will this debt build?’"
Identify My Fundability Gaps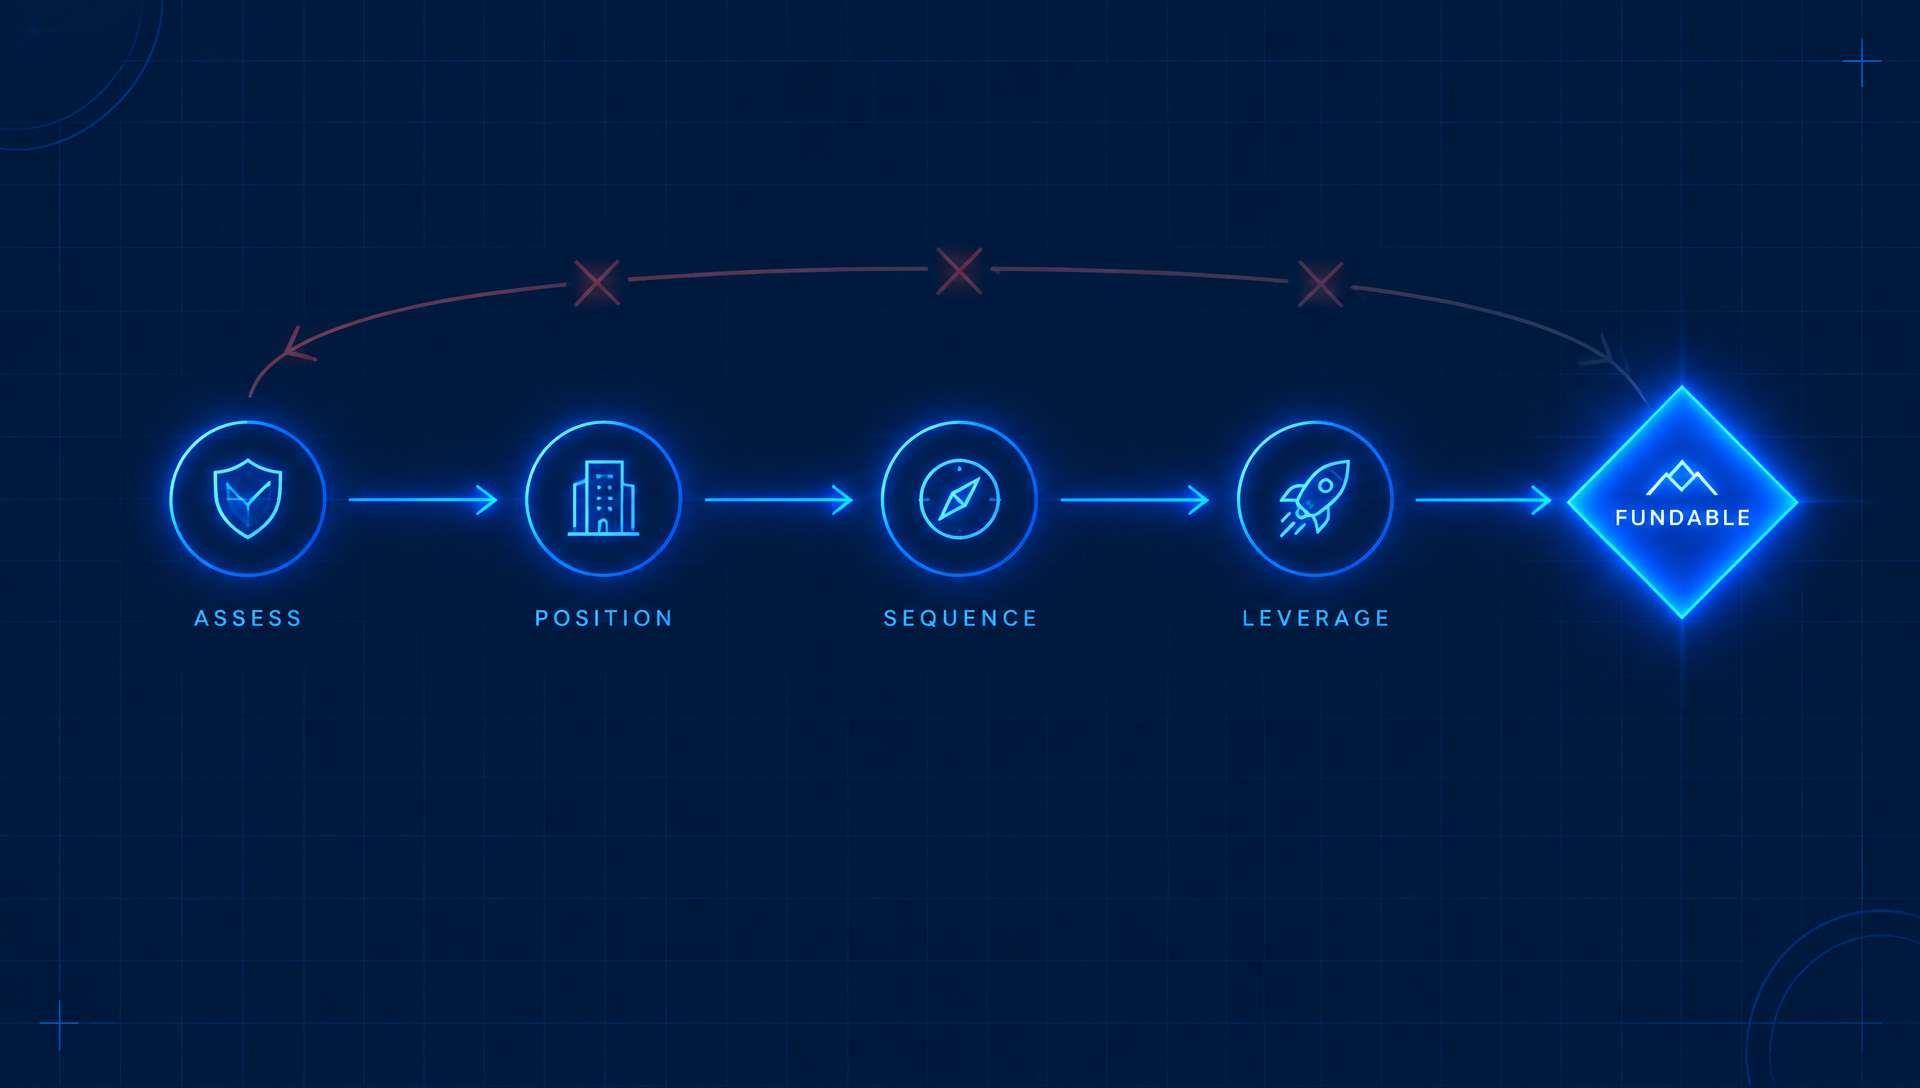
The Auxano Foundation Method™
No random applications. No one-size-fits-all lender list. Just a disciplined path from assessment to structure, positioning, and responsible leverage.
We review the factors that shape lender readiness—personal and business credit, debt load, utilization, cash flow, documentation, and stated capital goals.
We organize the entity, banking, documentation, and business-credit foundation so your profile is consistent, credible, and easier to evaluate.
We build a sequencing strategy around the financing products, lender criteria, timing, and use of funds that fit your actual profile and capacity.
We help you evaluate debt as a tool—not income—so borrowed capital supports productive assets, durable cash flow, and long-term ownership.
Watch Before Booking · 14 min
The connected reasons a lender may say "no"—and how to strengthen readiness before applying again
Free Training
Who We Help
You have revenue and a real operation, but repeated applications have produced denials, hard inquiries, and no clear explanation of what to strengthen first.
The Denied Owner
Established business, unclear profile gaps
Revenue is coming in, but daily or weekly payments consume the working capital needed for payroll, inventory, marketing, and growth.
The Cash-Flow Squeezed Owner
Strong sales, expensive existing debt
You want capital to acquire assets and create opportunity, but you do not want desperation to force unnecessary equity loss or poorly understood guarantees.
The Legacy Builder
Growth-minded, protective of ownership
You formed the business but still fund every expense personally—and need a sequence for banking, documentation, business credit, and lender readiness.
The First-Time Founder
Early stage, relying on personal resources
Auxano was built for people who were never taught how personal credit, business credit, entity structure, banking, cash flow, and lender criteria work together. Our purpose is to replace guesswork with a disciplined path toward capital, productive assets, ownership, and a legacy that can outlive one generation.
Programs
Fundability is not one score. It is the relationship between your personal profile, business profile, entity, banking, documentation, cash flow, debt load, and intended use of capital.
Compare bank, SBA, revenue-based, asset-backed, and other pathways against your profile, purpose, and repayment capacity.
Learn moreBuild the reporting, banking, documentation, and account-management foundation lenders may evaluate.
Learn moreEducation and strategy around utilization, debt load, profile depth, and the personal-credit factors lenders may evaluate. We do not provide credit repair.
Learn moreAlign state records, NAICS, EIN, banking, licenses, and core documentation into one consistent business profile.
Learn moreUnderwriter-level training so you stop guessing what lenders want and start speaking their language.
Learn more1-on-1 advisory on converting cheap capital into income-producing, generational ownership.
Learn moreAI-driven dashboards for fundability scoring, profile health, and pipeline visibility.
Learn morePractical guidance for owners building fundability, disciplined capital habits, and long-term ownership.
Learn moreWhy Auxano
Auxano helps you understand how lenders may view the complete picture, strengthen the parts you can control, and approach debt with a defined purpose. We do not dispute consumer-report items, promise score increases, lend money, or guarantee approvals.
Approval decisions, limits, rates, and terms are determined solely by lenders and vary by applicant and market conditions.
The Auxano Team
Fundability · Capital Strategy · Ownership
Market context: Federal Reserve 2025 Report on Employer Firms and Brown & Saunders, Journal of Entrepreneurial Finance. These figures describe the market, not promised client outcomes.
Free Download
A practical guide to the personal, business, and structural factors that may be standing between you and a lender-ready profile—before you submit another application.
FAQ
The Decision
Get a clear view of the personal, business, and structural factors shaping your readiness—then leave with an ordered roadmap for what to strengthen before your next application.